


Publication of Information as Required by Securities Registration and Issuance Regulation 2073 (Related to Sub Rule (1) of Rule 26)
Summary
(Subsidiary Co.). The Bank has 51% shareholding in Siddhartha Capital Limited (SCL) and SCL is licensed as a Mutual Fund Manager and Depository from Securities Board of Nepal (SEBON) as per Mutual Fund Regulation 2010 and also obtained the license for merchant banking business from SEBON in 2015.…
Auto-generated and may contain errors. Check the original notice before you act on it.
Files
- 44f08884-4117-4719-8bdd-227fc61d434b.pdfPDF · 2 pages · 92 KBOpen
Key details
- Organization
- Siddhartha Bank Ltd.
- Industry
- Health
- Category
- Acts & regulations
- Published
- Notice date
- Fiscal year
- FY 2083/84
- Source
- View on the original website
Text extracted automatically from the notice (may contain errors)
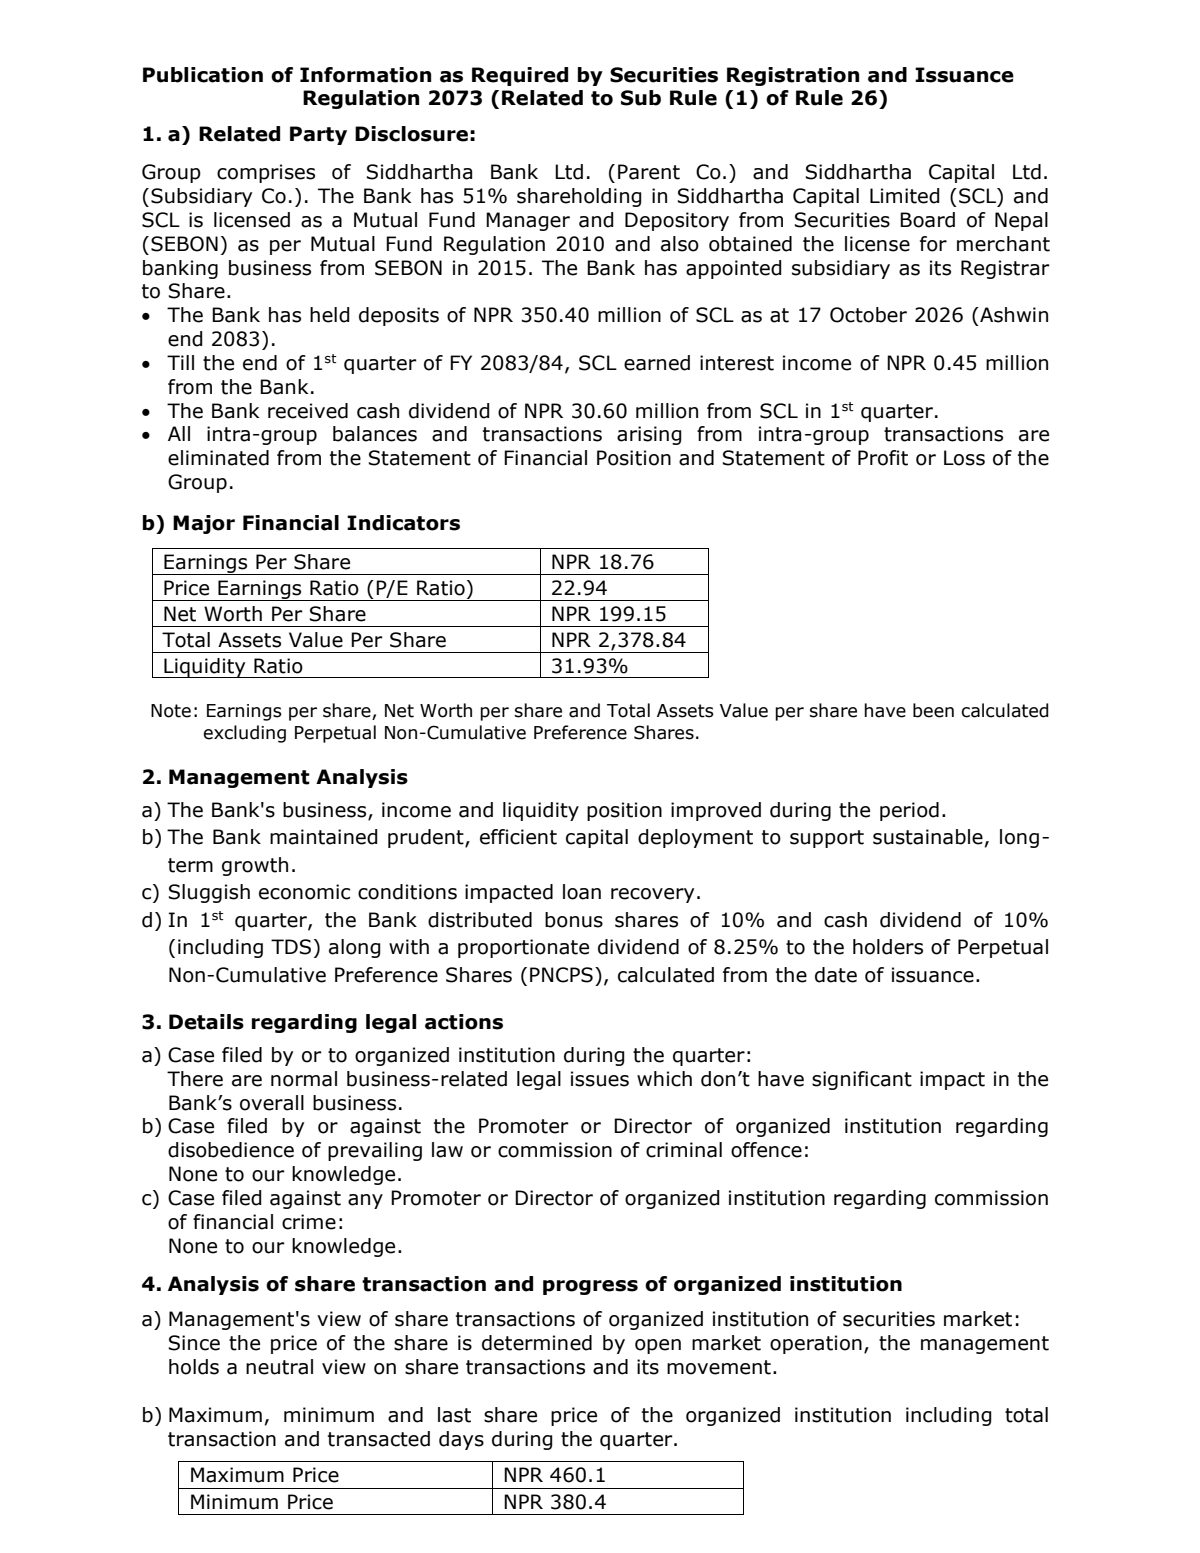
Publication of Information as Required by Securities Registration and Issuance Regulation 2073 (Related to Sub Rule (1) of Rule 26) 1. a) Related Party Disclosure: Group comprises of Siddhartha Bank Ltd. (Parent Co.) and Siddhartha Capital Ltd. (Subsidiary Co.). The Bank has 51% shareholding in Siddhartha Capital Limited (SCL) and SCL is licensed as a Mutual Fund Manager and Depository from Securities Board of Nepal (SEBON) as per Mutual Fund Regulation 2010 and also obtained the license for merchant banking business from SEBON in 2015. The Bank has appointed subsidiary as its Registrar to Share. • The Bank has held deposits of NPR 350.40 million of SCL as at 17 October 2026 (Ashwin end 2083). • Till the end of 1st quarter of FY 2083/84, SCL earned interest income of NPR 0.45 million from the Bank. • The Bank received cash dividend of NPR 30.60 million from SCL in 1st quarter. • All intra-group balances and transactions arising from intra-group transactions are eliminated from the Statement of Financial Position and Statement of Profit or Loss of the Group. b) Major Financial Indicators Earnings Per Share NPR 18.76 Price Earnings Ratio (P/E Ratio) 22.94 Net Worth Per Share NPR 199.15 Total Assets Value Per Share NPR 2,378.84 Liquidity Ratio 31.93% Note: Earnings per share, Net Worth per share and Total Assets Value per share have been calculated excluding Perpetual Non-Cumulative Preference Shares. 2. Management Analysis a) The Bank's business, income and liquidity position improved during the period. b) The Bank maintained prudent, efficient capital deployment to support sustainable, long- term growth. c) Sluggish economic conditions impacted loan recovery. d) In 1st quarter, the Bank distributed bonus shares of 10% and cash dividend of 10% (including TDS) along with a proportionate dividend of 8.25% to the holders of Perpetual Non-Cumulative Preference Shares (PNCPS), calculated from the date of issuance. 3. Details regarding legal actions a) Case filed by or to organized institution during the quarter: There are normal business-related legal issues which don’t have significant impact in the Bank’s overall business. b) Case filed by or against the Promoter or Director of organized institution regarding disobedience of prevailing law or commission of criminal offence: None to our knowledge. c) Case filed against any Promoter or Director of organized institution regarding commission of financial crime: None to our knowledge. 4. Analysis of share transaction and progress of organized institution a) Management's view of share transactions of organized institution of securities market: Since the price of the share is determined by open market operation, the management holds a neutral view on share transactions and its movement. b) Maximum, minimum and last share price of the organized institution including total transaction and transacted days during the quarter. Maximum Price NPR 460.1 Minimum Price NPR 380.4Closing Price NPR 430.5 Total Traded Shares 9,581,861 Total Transaction No. 21,633 Total Traded Days 61 Days 5. Problems and Challenges Internal a) Rising NPLs and higher provisioning, pressuring asset quality and profit. b) Slow economic momentum limiting quality loan growth. c) Limited scope for fees income generation amid competitive pricing and subdued transactions. d) Difficulty in attracting and retaining skilled human resources. e) Rising operational cost and increasing overall cost of doing business. External a) Competition among BFIs, squeezing margins. b) Weak credit demand and excess liquidity in the industry. c) Limited investment avenues and lower yields. d) Rising cybersecurity and operational risks. e) Global uncertainty and geopolitical developments affecting trade. Strategies to overcome Challenges a) Active liquidity management and lower cost of funds to protect margins. b) Digital transformation through automation, AI and analytics. c) Lean processes and cost optimization. d) Strengthening cybersecurity and IT infrastructure. e) Intensifying recovery and portfolio monitoring to contain NPAs. f) Product innovation and personalized digital solutions. g) Revenue diversification. h) Strong capital buffers. 6. Corporate Governance • Corporate governance is a core pillar of the Bank’s integrity and resilience, promoting transparency, accountability and sound decision-making. • Board of Directors provides strategic direction, aligning long-term objectives with regulatory requirements and stakeholder interests and regularly reviews governance standards. • Board-level committees - Risk Management Committee, Audit Committee and AML/CFT Committee ensure prudent risk oversight, strong internal controls and ethical compliance. • Management level committees – Executive Committee, Management Credit Committee, Asset Liability Management Committee (ALCO), Operational Risk Management Committee and Financial Direction Committees execute strategy, ensure sound credit decisions, manage liquidity and operational efficiency and mitigate risks. • Significant risks are identified, assessed and mitigated through a comprehensive internal control framework. Compliance culture is reinforced through internal audit, transparent disclosures and continuous staff training on governance and ethics. 7. Declaration by CEO I, CEO of the Bank, take responsibility for the truthfulness of the information and details disclosed in this report. I also hereby declare that to the best of my knowledge and belief, the information disclosed in this report are true, fair and complete and have not concealed any matters that can adversely affect the investment decision of the investors.
 Like
0
 Views
0
 Comments
0
 Share
0

Save

Report